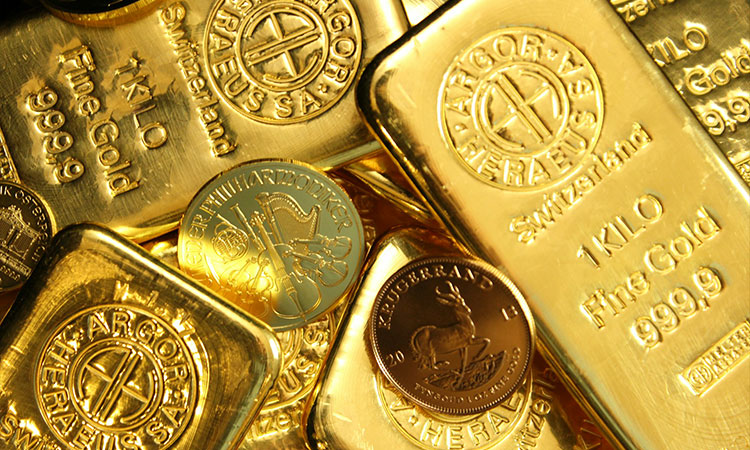
Where Is Gold (XAU/USD) Headed? Dollar Strength, Fed Policy and Geopolitical Uncertainty: A Record-Breaking Rally or a Deeper Decline?
Written by: Rania Gule, Senior Market Analyst at XS.com – MENA
Gold is trading in an increasingly critical phase, caught between mounting monetary pressures and geopolitical risks, as the precious metal struggles to regain its bullish momentum despite persistent uncertainty across global markets. In my view, the current price action represents more than just a temporary correction in gold prices. It reflects a significant shift in the forces shaping the market, with the US dollar regaining prominence, expectations of prolonged restrictive monetary policy from the Federal Reserve intensifying, and US Treasury yields rising. Together, these factors are putting gold to a serious test, challenging buyers’ ability to defend current price levels.
The outlook becomes even more complicated as gold moves toward the $ 3,820-per-ounce region, a technically significant area on the market’s price map, particularly after recent recovery attempts failed to trigger a meaningful reversal in the broader trend. Trading near previous lows does not necessarily mean that prices are positioned for a strong rebound. Instead, it may signal continued distribution and selling pressure, especially when recovery attempts coincide with a stronger US dollar and rising expectations of tighter monetary policy. Against this backdrop, I believe the key question is no longer whether gold can stage a temporary rebound, but whether it can regain the fundamental support that fueled its previous bullish rallies.
At the forefront of these developments is the US dollar, which has staged a notable recovery, climbing to levels not seen in approximately 19 months. The greenback has benefited from increased demand for US assets amid escalating geopolitical tensions, as well as shifting expectations surrounding the Federal Reserve’s monetary policy. The implications for gold are significant, as a stronger dollar makes the precious metal more expensive for investors holding other currencies, while simultaneously reducing its relative investment appeal compared with US dollar-denominated assets. However, the impact goes beyond currency valuation. If the dollar’s strength persists, it could create a double headwind for gold by weakening investment demand and undermining buying momentum across global markets.
Perhaps the most important factor in determining gold’s next move is the Federal Reserve’s policy stance and the evolving outlook for US interest rates. Recent hawkish remarks from several central bank officials highlight persistent concerns about inflation, particularly as price pressures remain above the Fed’s target levels. These signals have brought the prospect of interest rates remaining elevated for longer back into focus, while also leaving the door open to further monetary tightening if incoming economic data warrants such action. In my view, markets may have already begun repricing the Federal Reserve’s policy outlook, helping explain much of the recent strength in the US dollar and the decline in gold’s investment appeal.
This equation cannot be separated from US Treasury yields, which have emerged as another major challenge for gold. Rising yields, particularly on longer-dated government bonds, increase the opportunity cost of holding a non-yielding asset such as gold, encouraging some investors to reallocate their portfolios toward fixed-income instruments. The yield on the benchmark 10-year US Treasury note has moved above the 5% threshold, reflecting a clear shift in market expectations regarding inflation and the future path of interest rates. This development is not merely a short-term negative for gold; it also highlights investors’ growing sensitivity to persistent inflation risk, potentially extending the period of pressure on assets that do not generate regular income.
Recent US inflation data have reinforced these concerns, with October figures pointing to continued price pressures. Annual producer price inflation climbed to 6.5%, while the core measure rose 5%. Although moderation in some monthly components may offer markets some optimism, the broader picture still suggests that bringing inflation back to the Federal Reserve’s 2% target could prove challenging. Consequently, any upcoming economic reading that exceeds expectations could revive bets on further interest rate hikes, providing additional support for the US dollar and Treasury yields while exposing gold prices to another wave of selling pressure.
One of the most striking aspects of the current market environment is that geopolitical tensions, which traditionally support demand for gold as a safe-haven asset, have so far failed to halt its decline. Escalating tensions between Iran and the United States, along with growing concerns over maritime security and energy supplies across the Gulf region, are heightening uncertainty and supporting demand for defensive assets.
However, the strength of the US dollar is competing directly with gold for these safe-haven flows. Furthermore, any increase in energy prices resulting from supply disruptions could reignite inflationary pressures, potentially strengthening the case for tighter monetary policy. This is where the current market environment becomes particularly challenging for gold. Geopolitical tensions could shift from being a direct source of support for the precious metal to an indirect headwind if they trigger higher oil prices, rising inflation, and stronger US Treasury yields.
At the same time, I do not believe that dismissing the bullish scenario for gold would provide a balanced assessment of the market. The precious metal still has several strategic drivers that could reshape its medium- and long-term outlook. These include continued central bank purchases, efforts to diversify foreign exchange reserves away from the US dollar, growing concerns surrounding US debt and fiscal deficits, and the potential erosion of confidence in traditional financial assets if economic and geopolitical instability intensifies. Furthermore, prolonged international tensions could revive investment demand for gold once the pressures stemming from elevated Treasury yields and a stronger dollar begin to ease. Nevertheless, I believe these long-term supportive factors need a clear monetary policy catalyst to translate into a sustainable bullish rally rather than temporary rebounds within a broader downward correction.
Looking ahead, Federal Reserve Chair Kevin Warsh’s upcoming remarks and the minutes of the central bank’s previous meeting could prove pivotal in determining gold’s direction in the coming period. Markets are already pricing in elevated expectations of a 25-basis-point interest rate hike in December, while closely monitoring any signals that could reinforce or undermine these expectations. If Fed officials maintain their hawkish tone and continue emphasizing inflation as the primary policy concern, the US dollar could attract further support, leaving gold vulnerable to additional losses. Conversely, if policymakers signal a more flexible approach to the interest rate outlook, US Treasury yields could retreat, easing pressure on the precious metal and potentially allowing for a stronger corrective rebound.
In my view, the $3,820 region remains a key level when assessing downside risks, particularly as prices approach their lowest levels since October 2025. Recent trading activity suggests gold continues to struggle to reclaim the $3,900 mark, while holding above the $3,800 region tests buyers’ ability to absorb selling pressure. On the upside, recovering the $3,950 level, followed by $4,000, would be an important step toward improving the technical outlook and restoring confidence among bullish investors. However, a decisive break below major support could expose gold to a deeper correction, particularly if accompanied by continued strength in the US dollar and rising Treasury yields.
Overall, I believe gold is entering a genuine test of its underlying strength. While the prospect of a return to record highs remains intact from a strategic perspective, the precious metal faces significant monetary headwinds in the short term.
Markets do not reward gold simply because geopolitical risks are escalating. Instead, they respond to a far more complex balance between the US dollar, interest rates, Treasury yields, inflation and demand for safe-haven assets. For this reason, I remain cautious on gold, with selling pressure likely to persist unless we see a meaningful shift in expectations surrounding US monetary policy. A strategy of selling into rallies may therefore be more consistent with the current market environment, although the risks of sudden rebounds and unexpected geopolitical developments should not be overlooked. Ultimately, the question is not whether gold can reach new record highs, but when the monetary dynamics currently standing in its way will begin to change.
Zaid Barem / ymm


 Türkçe
 العربية
 English
 Deutsch
 Ελληνικά
 עִבְרִית
 Русский
 Українська