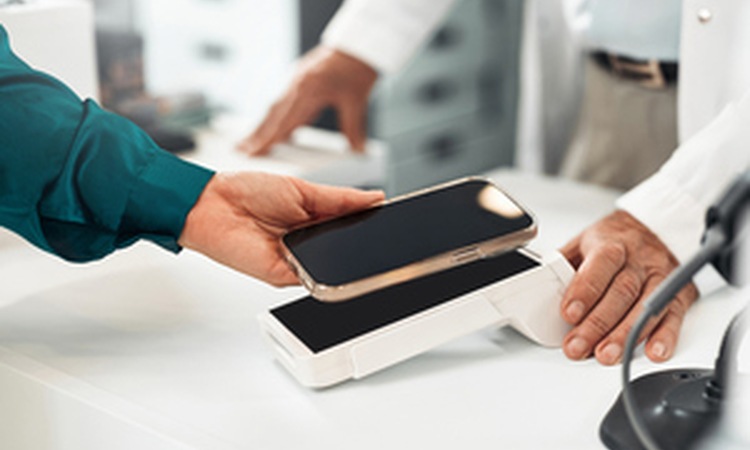
CMA outlines proposals to unlock contactless technology on Apple iPhone
Opening up iPhone contactless technology could boost innovation, lower costs and help UK fintechs grow.
- Apple’s fees and rules are blocking UK fintechs and other businesses from innovating and growing.
- Proposals expected to result in substantially lower access fees, helping make it commercially viable for more businesses to innovate and compete.
- Proposals would require Apple to grant access through the main contactless technology standards used internationally and give businesses more choice.
The Competition and Markets Authority (CMA) is consulting on proposals to transform how UK businesses build digital products and services on Apple’s iPhone.
The UK is one of the world’s leading fintech hubs, with the sector generating around £214 billion in turnover and supporting more than 360,000 jobs. Fintechs are a UK success story, but Apple’s fees and access rules for key mobile contactless technology, known as near field communication (NFC), risk blocking their ability to innovate and grow.
The CMA has heard concerns from businesses in the UK that Apple’s current NFC access arrangements may not be commercially viable, that fees, and other terms may be onerous, and that different technical approaches across jurisdictions and platforms can make it harder to scale and compete effectively.
Contactless services in the UK
Contactless technology is already central to everyday life in the UK. People increasingly use their phones to pay, travel, access buildings and hold important credentials. The increasing importance of this technology is clear from changes in contactless payments, currently the most popular use of this technology, which now represents 39% of all payments compared to just 3% of transactions a decade ago. Meanwhile, more than 60% of adults currently use a digital wallet, with Apple Wallet being the most popular choice in the UK.
However, unlike in the EU, not a single firm has launched a wallet-type product to compete with Apple’s in the UK. Just six months after Apple agreed to provide NFC access for payments in the EU, Vipps launched the first alternative payment app, followed by PayPal, Klarna, Curve, and BBVA.
The CMA wants to ensure that businesses in the UK with great ideas have a genuine opportunity to compete with existing wallets and develop the technologies and services of the future. Better access to the technology underpinning these services could help UK businesses develop a wide range of new products, such as account-to-account payments, digital IDs, travel passes and digital keys.
What the CMA is proposing
For businesses to compete effectively, access to the technology needs to work both technically and commercially. The CMA’s proposals therefore address two barriers: giving businesses access to the technologies they need and ensuring that access is available on terms which allow viable business models to develop.
Giving businesses a choice of technology: The CMA proposals would require Apple to provide access through the main contactless technology standards used internationally. Evidence seen by the CMA suggests that neither technology raises inherent security concerns and that access to both standards would support the widest range of innovative use cases and enable UK firms to roll out payment services that are already offered in the EU.
Making access commercially viable: Even where technical access is available, high fees can prevent businesses from developing viable products and competing effectively. Pricing is therefore a key part of ensuring that businesses have effective access to contactless technology. The CMA is not proposing to set the price and terms of contactless functionality access. Instead, it has proposed principles for how this should be determined, with the expectation that charges would be substantially lower than Apple’s current fees while still fairly rewarding Apple for providing access.
These proposals are consistent with the CMA’s proportionate approach to intervention and principles set out in digital markets legislation. The measures would help UK fintechs and other businesses seize the potential of this technology, which makes everyday experiences faster and more seamless. It will not only improve people’s lives now by offering more choice, but create the conditions for a new generation of contactless products and services to be developed in the future.
This could include:
- digital wallets and payment services
- digital IDs and age-verification tools
- digital car, hotel and workplace keys
- tickets and travel passes
- loyalty and rewards services
Sarah Cardell, Chief Executive of the CMA, said:
These proposals open the door to more innovation, more choice and economic growth, including in the UK’s important fintech sector.
We have heard that high fees, strict terms, and technical restrictions relating to Apple’s contactless technology make it too difficult for challengers to innovate and compete.
By removing barriers to entry, we can help create the conditions for brilliant British businesses with great ideas to develop new products and services here – from payment apps and digital IDs to travel passes and digital keys.
David Geale, Executive Director for Consumers, Payments and Competition at the FCA, said:
We welcome steps the CMA has taken to boost competition and innovation. Improved access and substantially lower fees should create greater competition and more choice for consumers and businesses.
Opening up this technology will also support the expansion of open banking, enabling more people to make payments directly from their bank accounts.”
The consultation will close on Tuesday 17 November 2026, and a final decision will be made after responses have been assessed. Visit the case page to find out more about the consultation and submit a response.
Notes
- The CMA is consulting on a proposed conduct requirement under the Digital Markets, Competition and Consumers Act 2024. The consultation follows the CMA’s designation of Apple as having Strategic Market Status in relation to its mobile platform.
- UK Finance (2026) estimates that contactless payments – whether made using a physical card or a mobile device – rose by 2% to 19.2 billion in 2025, representing 39% of all payments. A decade ago, contactless made up just 3% of transactions.
- The Data City (2025) estimates that the fintech sector employs 362,651 people across 3,348 companies and generates a combined turnover of £213.6 billion from 3,583 businesses.
- Which? (2026) found that 62% of UK adults currently use a digital wallet, with Apple Wallet (50%) being the most popular.
- The two main contactless technology standards used internationally are known as secure element (SE), which stores information on-device and host-based card emulation (HCE), which stores data off-device. Both HCE and SE are established technologies, not developed by Apple, and used across mobile ecosystems to enable a range of contactless services. Apple currently only offers SE in the UK, and the proposals mean that it would be required to offer both HCE and SE.
source: GOV

 Türkçe
 العربية
 English
 Deutsch
 Ελληνικά
 עִבְרִית
 Русский
 Українська